For long-term investors, one of the hardest decisions is not what to buy — but what to do when a good stock becomes volatile.
That is especially true for high-growth names such as Nvidia, where earnings, interest-rate expectations and broader market sentiment can all drive sharp short-term moves even when the long-term investment thesis remains intact.
For an investor who already owns 100 Nvidia shares and remains bullish for the long term, the question is therefore: how much short-term risk should the portfolio take?
There are a few obvious choices.
Sell some shares to lock in profits. Buy put options. Or simply stay invested and ride out the volatility.
There is now another possibility: keep the Nvidia shares, but temporarily short Nvidia Single Stock Futures against them.
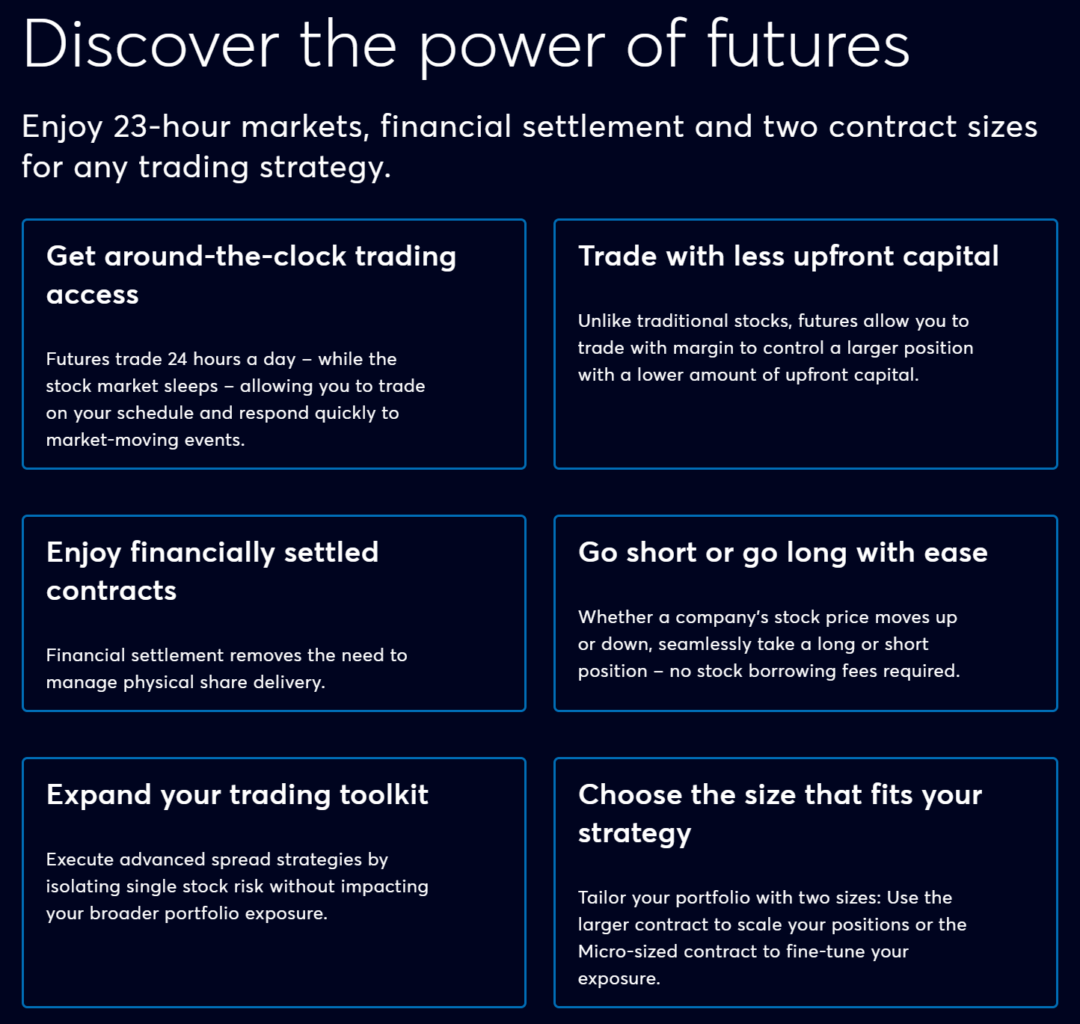
CME Group’s Single Stock Futures (SSF) suite now covers 55 U.S. stocks, including Nvidia, Tesla and SpaceX, with Micro contracts available on 22 of them.
Standard contracts represent 100 shares, while Micro contracts represent just 10 shares, giving retail investors more flexibility in how much exposure they want to hedge.
That is where SSFs become interesting.
For retail investors, the key attraction is not just leverage. It may simply be the ability to reduce short-term risk without having to sell a long-term winner.
This article is sponsored by CME Group. All views and opinions expressed are solely those of Financial Horse and do not represent those of CME Group or its affiliated institutions. Please refer to the end of the article for the full disclaimers and disclosures.
What exactly is a Single Stock Future (SSF)?
A Single Stock Future is simply a futures contract linked to the price of one company’s shares.
If Nvidia rises, Nvidia futures would generally be expected to rise. If Nvidia falls, Nvidia futures would generally be expected to fall.
CME offers two contract sizes. A standard SSF represents 100 shares, while a Micro SSF represents 10 shares for selected stocks.
CME currently lists 55 standard Single Stock Futures and 22 Micro contracts, including names such as Nvidia, Tesla and SpaceX.
Suppose Nvidia shares trade at US$200 and, for this hypothetical example, Nvidia futures trade at US$201.
The futures price reflects financing costs and expected dividends until expiry, so it can differ from the share price.
Notional exposure is calculated using the futures price:
Standard Nvidia SSF
US$201 × 100 = US$20,100 notional exposure
Micro Nvidia SSF
US$201 × 10 = US$2,010 notional exposure
The contracts expire quarterly in March, June, September and December, with two consecutive quarterly contracts listed at any one time. They are cash-settled, so expiry does not involve taking delivery of the underlying shares.
Why could this matter for Singapore investors?
The most obvious reason is timing.
CME Single Stock Futures trade from 5:00 p.m. to 4:00 p.m. Chicago time, Sunday to Friday, with a one-hour daily maintenance break.
For Singapore investors, the regular trading week runs from Monday morning to Saturday morning. Sessions begin Monday through Friday at 6:00 a.m. during US daylight saving time and end at 5:00 a.m. the following day, with a one-hour maintenance break between weekday sessions. During US standard time, these hours shift to 7:00 a.m. to 6:00 a.m. the following day.
This matters because US companies often release earnings and other important announcements after the cash market has closed.
An Nvidia or Tesla earnings release—or a material SpaceX operational update—could move the relevant stock during Asian hours. An investor may still want to own the company for the next three years, but prefer to carry less exposure until the market has absorbed the news.
For investors with access through an eligible futures broker, CME SSFs provide a way to adjust that exposure during the Singapore trading day.
Liquidity and bid-ask spreads can still vary outside regular US market hours, so the live market should be checked before trading. As the contracts are settled in US dollars, investors should also maintain sufficient USD liquidity for potential margin requirements.
For Singapore investors, this extended trading window provides a practical bridge between US after-hours announcements and the reopening of the underlying stock market.
How would an Nvidia hedge actually work?
Take the same investor with 100 Nvidia shares.
For this hypothetical example, assume:
Nvidia share price = US$200
Nvidia futures price = US$201
The futures price is slightly higher to reflect financing costs, less expected dividends, until the contract expires.
The investor holds:
100 shares × US$200 = US$20,000 of Nvidia exposure
Suppose earnings are approaching and the investor wants to substantially reduce that exposure for a few days without selling the shares.
One option is to short one standard Nvidia SSF, representing 100 shares.
If Nvidia falls 10%
The share price falls from US$200 to US$180.
The 100 shares lose:
US$20 × 100 = −US$2,000
Suppose the futures price falls from US$201 to US$181.
The investor sold the futures at US$201 and can now buy them back at US$181, gaining:
US$20 × 100 = +US$2,000
The futures gain offsets the loss on the shares.
Net economic impact ≈ zero before costs.
For simplicity, this example keeps the gap between the futures and share prices at US$1. In practice, that gap can change, so the offset may not be exact. Fees and bid-ask spreads also affect the result.
The investor still owns the Nvidia shares, but the price exposure has been largely neutralised while the hedge is in place.
What if Nvidia rises 10% instead?
The reverse happens.
The share price rises from US$200 to US$220, producing a US$2,000 gain.
If the futures price rises from US$201 to US$221, the short futures position loses US$2,000.
Again, the gains and losses offset each other before costs, assuming the price gap stays unchanged.
This is the most important point to understand about a futures hedge:
It reduces the downside on the portion being hedged, but it also offsets the upside.
There is no free protection.
What if only half the position needs to be hedged?
This is where Micro SSFs become useful.
Suppose the investor does not want to eliminate Nvidia exposure completely. The goal is simply to reduce it by half.
One Micro Nvidia SSF represents 10 shares.
So:
5 Micro SSFs × 10 shares = 50 shares hedged
The investor is now effectively exposed to roughly 50 Nvidia shares instead of 100.
If Nvidia falls, approximately half the downside is hedged.
If Nvidia rises, approximately half the upside remains.
The sizing formula is straightforward:
Number of contracts = Shares held × Desired hedge percentage ÷ Contract multiplier
For an investor with 100 Nvidia shares using the 10-share Micro:
30% hedge: 100 × 30% ÷ 10 = 3 Micro contracts
50% hedge: 100 × 50% ÷ 10 = 5 Micro contracts
80% hedge: 100 × 80% ÷ 10 = 8 Micro contracts
This ability to adjust exposure in 10-share increments is one of the more practical features of Micro SSFs for retail investors.
CME describes Micro SSFs as allowing traders to scale into and out of positions more precisely, rather than taking exposure in a full 100-share block.
The portfolio question therefore changes from:
“Should Nvidia be sold?”
to:
“How much Nvidia exposure is desirable right now?”
That is a more useful way to think about risk.
Try it yourself with the CME Trading Simulator
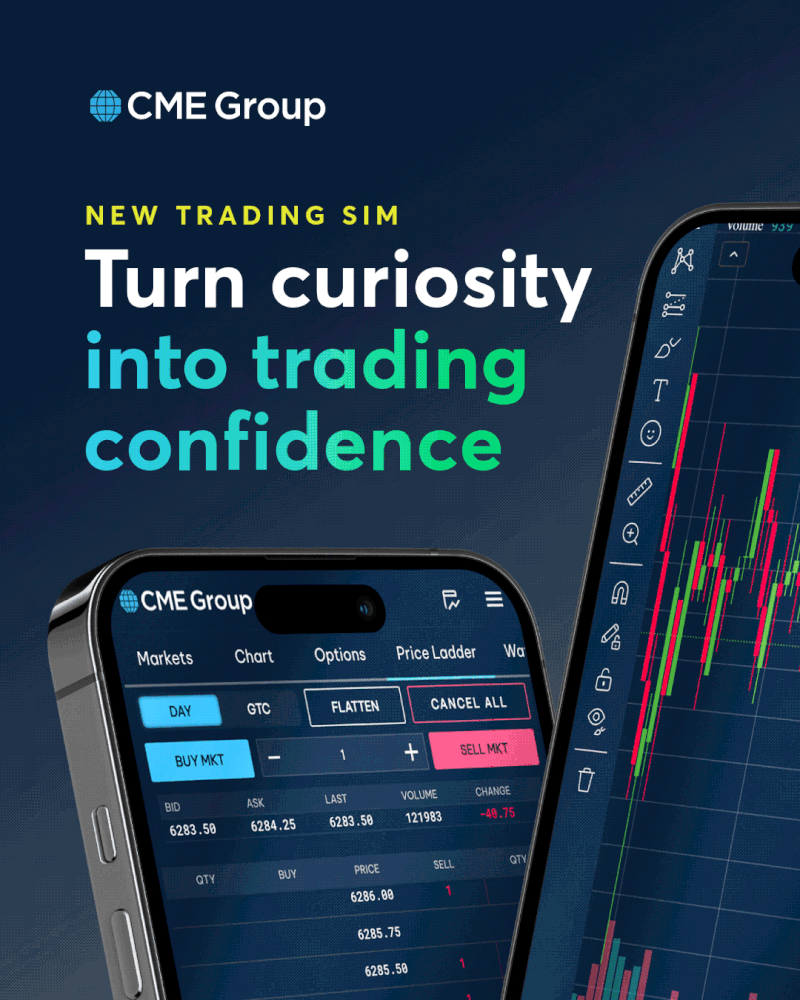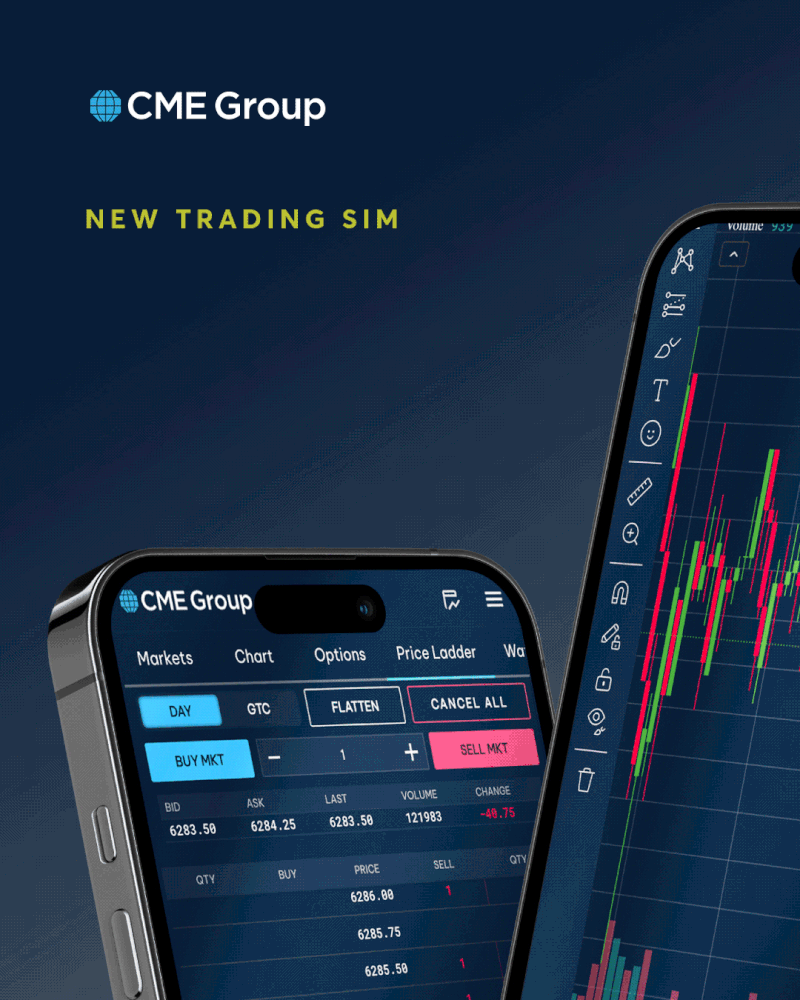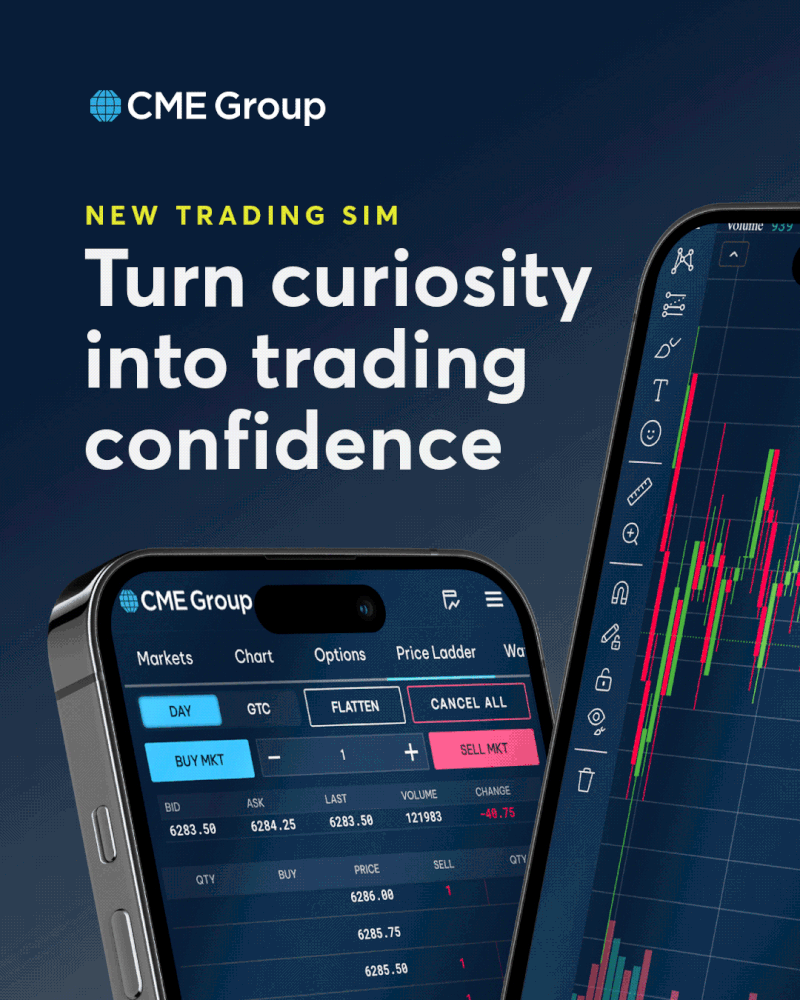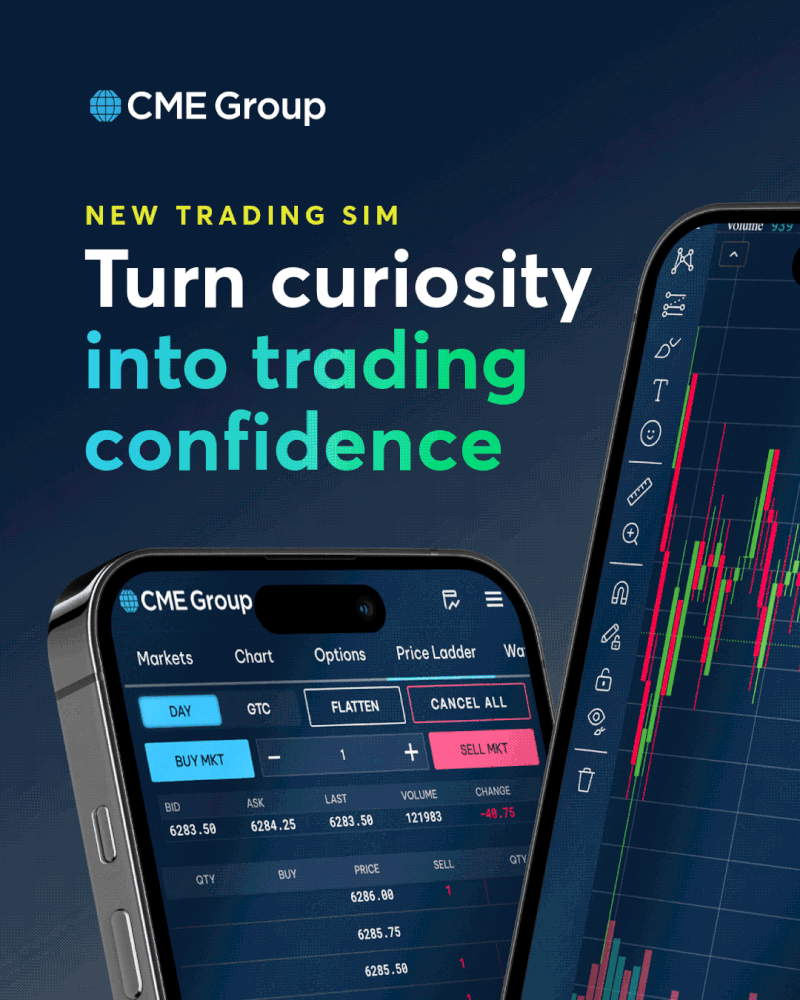
Explore the free CME Trading Simulator to give futures trading a try.
Experiment with different position sizes, test strategies and see how your positions respond to market moves.
It is a useful hands-on way to get familiar with futures before putting on a real hedge.
Why use an SSF instead of buying a put?
This is probably the most important comparison for an investor hedging around earnings.
A put option provides protection in a different way.
Suppose Nvidia is at US$200 and an investor buys a put. If Nvidia falls sharply, the put can rise in value and help offset the loss on the shares.
The big advantage is that the investor can protect the downside while still keeping the upside if Nvidia rallies.
The level and duration of protection depend on the put’s strike price and expiry.
But that protection has a price: the option premium.
Around earnings, options may also become more expensive because the market is already expecting a large move. After the earnings announcement, that uncertainty can disappear quickly, causing implied volatility to fall. Time decay also reduces the value of an option as it approaches expiry.
CME illustrates this with a hypothetical Tesla earnings example. The put helped cushion the loss when Tesla shares fell, but falling implied volatility and time decay limited the put’s gain in value.
A short Tesla SSF would have provided a more direct hedge, without option time decay or sensitivity to implied volatility. The trade-off is that it would also have offset gains on the hedged portion if Tesla had rallied.
An SSF has a simpler payoff.
There is no option premium paid upfront, no theta decay, no implied-volatility exposure and no strike price to choose. The exposure is essentially linear.
So the choice can be thought of this way:
Put option: pay for downside protection while keeping the upside.
Short SSF: reduce exposure more directly, but also give up upside on the portion being hedged.
Neither is universally better.
If the priority is defined downside protection while keeping the upside, a put may be more suitable.
If the objective is simply to temporarily reduce directional exposure, an SSF can be a simpler tool.
Why not just sell the shares?
Sometimes selling is still the right answer.
If the long-term investment thesis has changed, using a derivative to avoid selling the underlying does not solve the real problem.
But that is different from an investor who still likes Nvidia over the next three years and is simply uncomfortable with the amount of risk around one earnings announcement.
A temporary futures hedge allows the investor to adjust that exposure while retaining the shares.
There is still a timing decision to make.
A full hedge largely offsets any rally while it remains open, so the investor must decide when to remove it. A partial hedge leaves some exposure to both gains and losses.
The practical distinction is between two questions:
Should Nvidia still be owned for the next three years?
And:
Should the portfolio carry 100% of the Nvidia exposure over the next seven days?
The answers do not necessarily have to be the same.
SSFs vs. alternatives
| Shares | Single Stock Futures | Single-stock options (long put) | Equity ETFs | |
| Exposure | Linear; individual company | Linear; individual company | Non-linear; individual company | Generally linear; basket of stocks |
| Ownership | Own company shares | No share ownership | No share ownership | Own units in a fund |
| Upfront capital | Full purchase price, or margin if eligible | Margin; minimum 15% of notional exposure for outright positions, with actual requirements potentially higher | Option premium | Full purchase price, or broker-set margin; requirements may be higher than SSFs |
| Time decay | No | No option time decay | Generally loses time value as expiry approaches | No option time decay; fund fees apply |
| Sensitivity to option implied volatility | No | No | Yes | No |
| Taking short exposure | Usually requires stock borrowing and broker approval | Sell futures; no stock borrowing required | Buy a put; provides non-linear downside exposure | Requires ETF borrowing and broker access; availability can constrain shorting around market events |
| Expiry | None | Quarterly | Specified expiry date | Generally none |
| Structure | Listed shares | Exchange-traded futures | Listed options | Exchange-traded fund |
| Main risks | Share-price losses; additional risks if shorted or leveraged | Leverage, margin calls and differences between futures and share prices | Premium loss, time decay and changes in implied volatility | Market losses and tracking error; additional risks if shorted or leveraged |
Note: This table provides a simplified general comparison for informational purposes only and does not constitute a recommendation. For Singapore investors, product access, margin requirements, borrowing availability, costs and tax treatment vary by broker, account, instrument and applicable rules. The 15% SSF margin requirement is a regulatory minimum, not a guaranteed broker rate. ETF comparisons refer to conventional, unleveraged equity funds, excluding inverse, leveraged and options-based ETFs. ETF borrowing is not guaranteed, and ETF margin requirements are not universally higher than those for SSFs. A diversified ETF may not closely hedge an individual stock. SSFs have no option time decay, but financing costs and expected dividends affect their pricing. A short SSF hedge offsets both downside and upside on the portion hedged. Lower margin does not mean lower risk. Investors should assess suitability and review the relevant product and broker documentation before trading.
SSFs provide simple, linear exposure to an individual stock through a futures contract.
Compared with shorting an ETF, selling an SSF does not require borrowing shares. ETF shorting depends on broker access and borrowing availability, which can limit your ability to put on a hedge around a major market event.
SSFs may also require less upfront margin than an ETF position, although the actual difference depends on the instrument, broker and account.
For investors looking to temporarily hedge an individual stock, that flexibility can be attractive.
But lower upfront capital does not mean lower risk. That brings us to one of the most important features investors need to understand: margin.
Low margin does not mean low risk
Unlike buying 100 shares outright, an investor does not pay the full value of an SSF position upfront.
Instead, margin is posted.
CME states that, under CFTC and SEC regulations, initial and maintenance margin for an outright long or short SSF position must be at least 15% of the contract’s current notional value. Actual margin requirements may be higher depending on CME Clearing and the broker.
Source: CME Group SSF FAQ
Using the same hypothetical Nvidia futures price of US$201:
US$201 × 100 shares = US$20,100 of futures exposure
At the 15% minimum:
US$20,100 × 15% = US$3,015 minimum margin
That is what makes futures capital efficient.
But it does not mean the investor only has US$3,015 of risk.
The contract still represents US$20,100 of exposure.
As in the earlier example, a US$20 move in the futures price produces:
US$20 × 100 shares = US$2,000 gain or loss on the futures position
For the investor who is short, a rise creates a loss and a fall creates a gain.
So the key distinction is:
Margin deposited ≠ size of the position ≠ maximum loss
Margin is collateral.
It does not cap the loss.
This is why futures can be useful for hedging — but dangerous when leverage is used carelessly.
Even a good hedge can create a cash problem
There is another point that is easy to overlook.
Suppose an investor owns 100 Nvidia shares at US$200 each and shorts one standard Nvidia SSF.
Nvidia then rises 20% to US$240.
The shares gain US$4,000.
Assuming the futures price rises by the same US$40, the short futures position loses US$4,000.
Economically, the hedge is doing exactly what it is supposed to do.
But the US$4,000 gain on the shares does not automatically appear as cash in the futures account.
The futures loss may still create additional margin requirements that need to be funded.
So even a correctly constructed hedge can create a liquidity problem if there is not enough spare cash available.
The practical takeaway is simple:
The margin buffer should always be sized together with the hedge.
What other risks need to be considered?
The main risks are not especially complicated, but they should be understood before trading.
Basis risk. The futures price will not always be exactly the same as the share price. Interest rates, expected dividends and time to expiry affect futures pricing.
Liquidity. A contract may trade for 23 hours, but liquidity and bid-ask spreads can differ substantially depending on the stock and time of day.
Expiry. SSFs expire quarterly. If a hedge needs to remain in place, it may have to be rolled into the next contract.
Corporate actions. Stock splits, special dividends, mergers and other corporate actions may result in adjustments to the futures contract.
Currency. CME SSFs are financially settled in U.S. dollars, so Singapore investors measuring their wealth in SGD should also consider USD/SGD exposure.
None of these makes SSFs inherently unsuitable. They simply mean the hedge needs to be planned rather than treated as a set-and-forget position.
When could SSFs be useful?
For retail investors, one of the clearest use cases is temporary hedging around a specific event.
Tesla illustrates why the timing of the hedge matters. Its production and delivery figures are released before its full financial results, creating two separate periods of uncertainty.
An investor could hedge through the delivery announcement only, or keep the hedge in place through earnings. The longer the hedge remains, the longer both the downside and upside are offset.
SpaceX presents a different situation.
As a newly listed stock, it has a much shorter public trading history. Its share price may therefore be influenced not only by business fundamentals, but also by price discovery and index-related flows. CME noted that the company’s June 2026 IPO triggered significant index supply pressures.
In this case, getting the contract count right may not be enough. The bid-ask spread, market depth and difference between the futures and share prices will also affect how efficiently the position can be hedged.
Another possible use is managing concentration risk.
A stock that started as 5% of a portfolio may have grown to 15% after a strong rally. The long-term investment case may still look attractive, but the position has become much more important to overall portfolio returns.
A partial futures hedge can temporarily reduce that concentration without forcing an immediate sale. However, if the investment thesis has changed permanently, selling the shares may be the more direct solution.
The extended trading window may also be useful when material news breaks outside regular US market hours. Subject to liquidity and spreads, an investor can adjust the exposure before the US cash market reopens.
More experienced traders may also use SSFs to manage the directional exposure of an options portfolio or construct relative-value trades. These strategies require more careful sizing and introduce additional correlation and basis risk.
For many investors, however, the most practical use remains straightforward: temporarily adjusting the amount of single-stock risk in a portfolio without selling the underlying shares.
When may SSFs be unsuitable?
SSFs will not suit every investor or every situation.
They may be less appropriate where the investor cannot comfortably meet additional margin requirements, does not want to actively monitor the position, requires a clearly defined maximum loss, or is trading a contract with limited liquidity.
They are also a poor fit if the main attraction is simply the ability to control a large amount of exposure with relatively little upfront capital.
That is where the same capital efficiency that makes futures useful can also become a risk.
Capital efficiency should not be confused with lower risk.
A useful new tool for managing single-stock risk
For investors with large positions in stocks such as Nvidia or Tesla, Single Stock Futures offer another way to manage short-term risk without having to sell a long-term holding.
The idea is straightforward: decide how much exposure to keep, and hedge the rest.
Micro contracts allow that hedge to be adjusted in smaller 10-share increments, while the extended trading window provides more flexibility outside regular US market hours.
The trade-off is that the hedge offsets upside as well as downside on the portion hedged. Investors must also maintain sufficient cash to fund futures losses and meet margin requirements, even when their shares are gaining value.
Used thoughtfully, SSFs can be a useful addition to the retail investor’s toolkit—particularly when the long-term investment view remains intact, but there is a reason to temporarily reduce short-term risk.
The principle is simple:
Size the hedge around the risk you want to reduce, and have a clear plan for when to remove it.
A simple checklist before trading
Before putting on an SSF hedge:
- Know what you are hedging. How many shares are you trying to protect?
- Choose the hedge ratio. Do you want to hedge 30%, 50% or 100% of the position?
- Check the contract size. Is a standard 100-share contract or a 10-share Micro more suitable?
- Calculate the notional exposure.
Futures price × Contract multiplier × Number of contracts
- Keep a cash buffer. Make sure there is enough liquidity to meet potential margin calls.
- Check the live market. Look at the bid-ask spread, market depth, commissions and broker/exchange fees.
- Have an exit plan. Decide in advance when the hedge will be closed or rolled.
Once these points are clear, investors may then decide whether an SSF hedge makes sense for their objectives, risk tolerance and circumstances.
Where can Singapore investors trade CME Single Stock Futures?
For Singapore investors looking to trade CME Single Stock Futures, Moomoo Singapore is one option to consider.
Through the moomoo app, investors can access global markets and a range of investment products, alongside market data, research and trading tools to help them assess opportunities and manage their positions.
Moomoo also offers investor education resources and physical stores in Singapore, which may be useful for those who prefer to learn more about the platform in person.
As the market leader offering Single Stock Futures, FH readers can use this link to enjoy a welcome bonus on the Moomoo app.
Find out more: CME Group Single Stock Futures
For contract specifications, trading hours and margin details, see the CME Group SSF FAQ.
To learn more about Single Stock Futures: CME Group Equity Course Catalog
Disclaimers:
This article is sponsored by CME Group. All views and opinions expressed are solely those of Financial Horse and do not represent those of CME Group or its affiliated institutions.
This article is provided for general informational and educational purposes only. It does not constitute investment, financial, legal or tax advice, or a recommendation or solicitation to buy or sell any security, futures contract or other financial instrument. It does not take into account any investor’s objectives, financial situation or needs.
Futures are leveraged instruments, involve substantial risk and may not be suitable for all investors. Losses can exceed the initial amount deposited, and additional funds may be required at short notice.
All numerical examples are hypothetical and exclude commissions, exchange and broker fees, taxes, bid-ask spreads and other transaction costs. Contract specifications, margin requirements, liquidity, product availability and investor eligibility may vary by broker and jurisdiction and may change over time.
Investors should independently assess suitability and review the relevant exchange and broker documentation before trading. Independent professional advice should be obtained where appropriate.
Hi FH,
Comparing AI to the Dot-Com crash misses a key detail. Dot-com was full of zero-revenue startups with no business models like Pets.com. AI, on the other hand, is already generating actual revenue and boosting corporate margins for real businesses.
The real risk today isn’t fake business models—it’s whether the huge capex spending will deliver expected ROI before global demand catches up.
Regards,
Gerald
https://sgwealthbuilder.com