The price action in Sea Ltd this week was ugly.
Down 9% on Tuesday, on almost 4 times the normal volume.
Totalling 19% in 4 trading days, and the stock is now down 60% from its September 2025 high.
The trigger was a 700-word email from founder Forrest Li to his staff, marking 9 years since the IPO – saying that Monee (the fintech arm) may go for its own IPO, and that Sea will start selling its internal cloud to outside customers as “Sea Cloud”.
No capex number. No timeline. No customer.
Full disclosure – I hold Sea with an average price of around the US$100 mark, so I am underwater at current price, although the loss is not as bad as others as I know some investors with a much higher average price.
So… was the market right to panic, and will I sell my shares, or buy more?
What actually happened to Sea Ltd this week
Here’s the chart for reference.
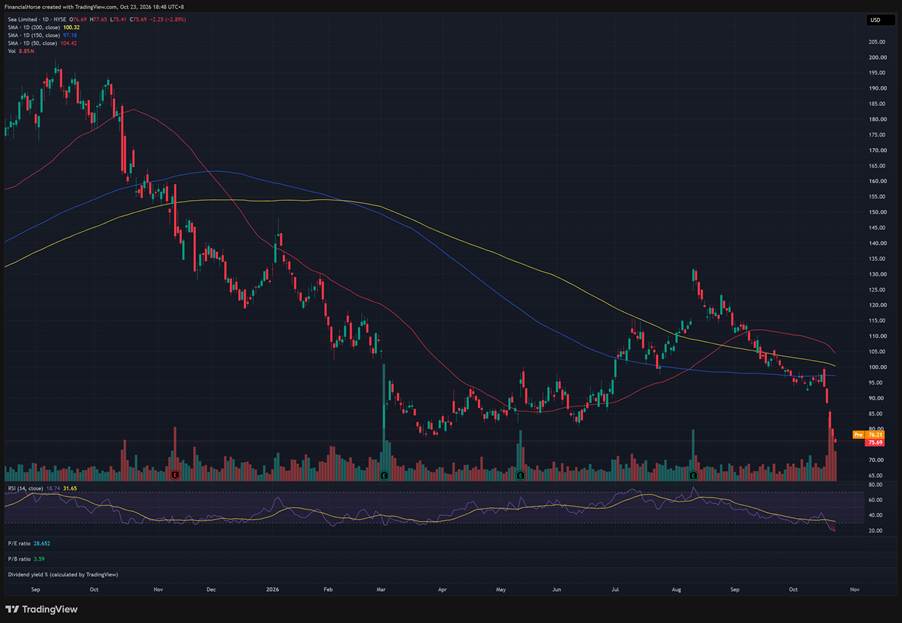
This is the price action day by day for reference:
| Date | Close (US$) | Change | Volume |
| Fri 16 Oct | 93.77 | −3.8% | 4.2M |
| Mon 19 Oct | 88.47 | −5.7% | 7.4M |
| Tue 20 Oct | 80.43 | −9.1% | 18.7M |
| Wed 21 Oct | 77.94 | −3.1% | 15.6M |
| Thu 22 Oct | 75.69 | −2.9% | 8.8M |
Couple of points to note.
First – Monday’s 5.7% drop happened before anyone had seen the letter, which only came out at 6am New York time on Tuesday.
Which kind of suggests some people knew what was coming.
Second – Tuesday was a Sea problem, not a market problem. Grab was up 0.7% that day, MercadoLibre up 2.2%, and the S&P 500 up 0.3%.
While Sea was down 9.1%
The market did not sell Southeast Asia or tech on Tuesday. It sold Sea.
The letter in question
Which brings us to the letter in question.
I thought it was important enough that I extracted the full letter below, emphasis mine:
Email Subject: Marking the 9th Anniversary of our IPO
Dear Sailors,
Nine years ago today, on October 20th 2017, we became a publicly listed company on the New York Stock Exchange.
I still remember standing on the NYSE podium that morning, waiting to ring the bell. It had been eight years from our founding in 2009 to that moment – eight years of hard work, sleepless nights, constant problem solving, and long stretches where we did not know whether we were going to make it or die trying. When the bell rang and the floor erupted, I felt a flood of joy and relief in equal measure. It remains one of the happiest days of my life.
That morning, I believed that we had won the race. I was wrong about that, and I’m glad I was.
Our IPO was not the finish line; it was the starting line. Everything we had done to build from nothing to something, to get big enough and good enough to list, had only earned us the right to compete. The bell I rang that day was not a victory bell, but a starting pistol!
Nine years on, here is where that race has taken us. Comparing our most recent quarter with the quarter in which we listed: Garena’s quarterly active users have grown almost 10 times, from 69 million to 666 million. Shopee’s quarterly GMV has grown 35 times, from $1.1 billion to $38.3 billion. And our quarterly revenue has grown more than 80 times, from $94 million to $7.8 billion.
All three of our businesses are well-scaled, profitable, and still growing. None of this would have been possible without going public. Listing gave us capital, gave us credibility, and let far more people contribute to – and share in – what we were building.
We may well ring that bell again! At our IPO, our financial services business was still tiny compared to where it is today. Since then, Monee has been running the same race we ran between 2009 and 2017– building something out of nothing, and working to make it big enough and good enough to go public.
We believe Monee is approaching the point where it can stand on its own two feet and begin its own race. Going public could give it the resources and the room to go further and faster than it can today.
We will keep building this way: wave after wave, cycle after cycle. From starting up, to listing, to racing – and then starting up again.
Let me tell you about our next start-up.
For more than ten years, we have quietly built and run our own cloud platform. It was never a side project. It is the backbone powering Garena, Shopee and Monee’s scale every single day, at a level of cost and reliability we could not have bought from anyone else.
Over the last two years, around 500 Sailors have been rebuilding that platform to power something new: the wave of AI applications rising across every part of Sea. Because of their work, taking an AI idea from a whiteboard to production inside our company is now dramatically faster than it was two years ago.
We are now going to offer that capability to the world. Its name is Sea Cloud.
When we built Shopee at the start of the mobile internet era, we made it mobile-first while much of our competition was still thinking in terms of websites. We believe AI is that moment again. Sea Cloud will be an AI-first enterprise platform, built by a team that has spent a decade running infrastructure at enormous scale, under real commercial pressure, for some of the most demanding consumer businesses in this region. That’s a credential that can’t be bought; it’s one you can only earn by operating.
Nine years ago, I could not have imagined where we would be standing today. And what strikes me most is not how far we have come, but that after all this time, we still have the aspiration to start again. This anniversary is meaningful to me not as a milestone to pass, but as a reminder of how we never stop running: we build something, get it to the starting line, and then start again. Our race is far from over. In many ways, we are only at the start of it.
There will be more bells. Every one of them will be a beginning, not an ending.
Happy IPO anniversary, Sea!
Sincerely,
Forrest
Why did Sea Ltd fall so much?
My first instinct was that this was all about the AI cloud.
AI cloud businesses require massive capex investment that even the likes of Microsoft and Google struggle to finance.
Sea’s Fintech and Shopee ecommerce arm are not exactly the most profitable businesses, to open up a new business line that requires significant capex is not what investors want to hear.
Then I slept on it, and I think the reality is a bit more nuanced.
If you ask me, the sell-off may come down to 3 reasons.
One – the stock was already breaking before the letter arrived.
Sea peaked at US$131 on results day in August. By last Friday it was US$94 – down 29% before this week even started.
Q2 revenue was up 48%, but earnings per share only 7.7% – below what analysts expected, for the fourth quarter in a row.
Then on 2 October, DBS cut Sea to Hold with a US$105 target, on the view that Shopee’s spending to hold off TikTok Shop “improves the moat but costs margins”.
In plain English – the market has been waiting 2 years for Sea to show profitability, and it is still waiting.
And the market has run out of patience – the stock has been selling off for a while now, even before the AI business was announced.
Two – the cloud announcement is big open ended capex bill
And then came the AI business.
To understand why this was so scary for investors, look at what running an AI cloud actually costs.
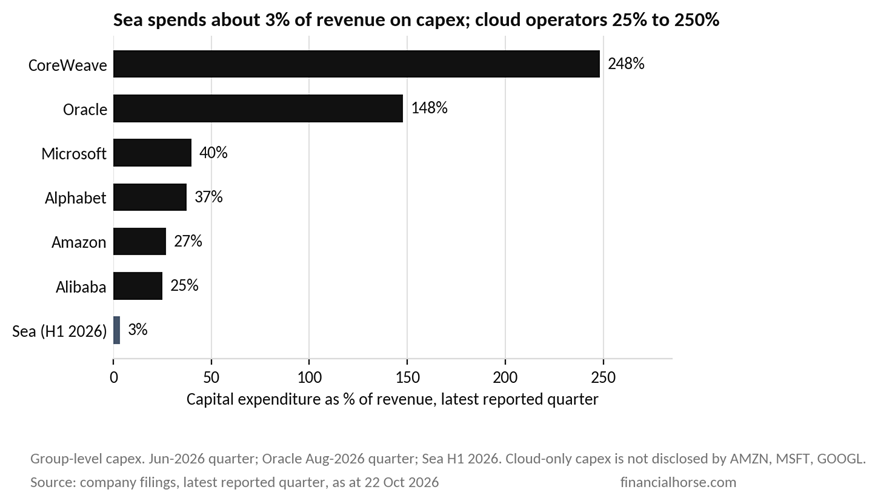
Sea spends about 3% of its revenue on capex today. Oracle spends more than its entire revenue, and CoreWeave 2.5 times.
Alibaba Cloud, the closest Asian analogue, took 11 years to turn a profit.
Now put that against Sea’s own cash flow.
Sea generated about US$2 billion of free cash flow in the first half of 2026 – but Monee’s loan book grew by US$2.9 billion in the same 6 months, and the buyback took another US$578 million.
In plain English – Sea’s fintech business, and eCommerce business, already require huge investments today.
All of which is being funded by Garena, which at this point is still basically 1 game.
And Sea just announced they would be opening a new business line, that also requires huge investment.
Into a market that is desperately looking for when Sea can turn a big profit.
Boy… in that context I can understand the reaction.
Three – the Monee IPO
Now this last one is interesting.
Here’s where Sea’s profits actually come from:
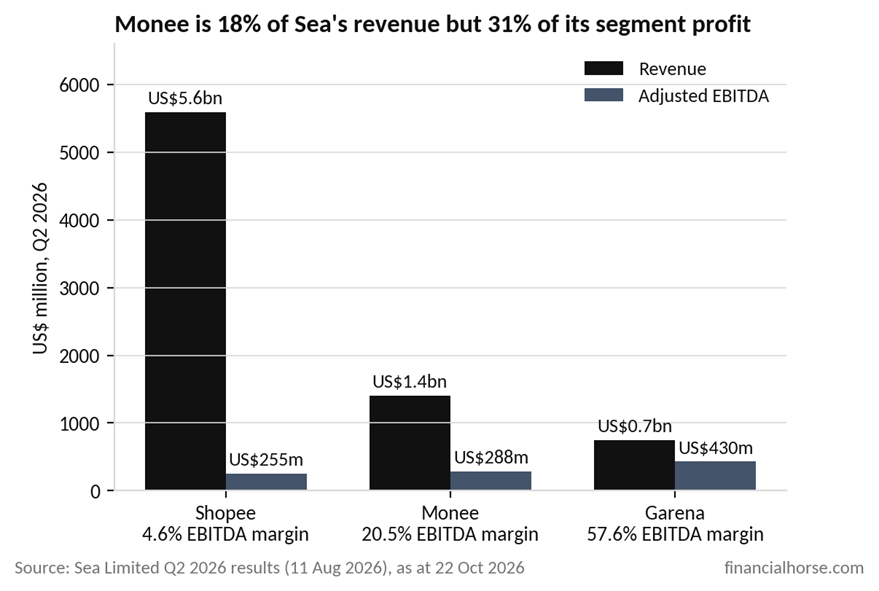
Monee is 18% of revenue but 31% of group profit, at a 20.5% margin.
Shopee is 72% of revenue at a 4.6% margin.
So the fear is obvious: list Monee, and what’s left is Shopee (which makes no money), plus Garena, which is one game.
Do you want to still own Sea then, or do you want to just own Monee?
But DBS values Monee at US$18–22 billion as a standalone, against roughly US$6 billion implied inside Sea today – so on that basis a listing would unlock about US$18 a share.
That said – GCash listed in Manila on Tuesday and closed flat, so the market is not paying up for Southeast Asian consumer credit right now. And DBS doesn’t expect a Monee listing before 2027 anyway.
So this last one is tricky – I think it’s arguable the Monee IPO could be a net positive for the stock.
The big reason for the sell-off, is probably the other 2 reasons above.
But I mean, this is just my view and I could be wrong.
Never miss a post! Follow Financial Horse on WhatsApp or Telegram — one tap, and every new article reaches you the moment it’s published.
What is priced in for Sea Ltd at US$78?
Which brings us to the million dollar question.
After a 60% fall, is Sea cheap?
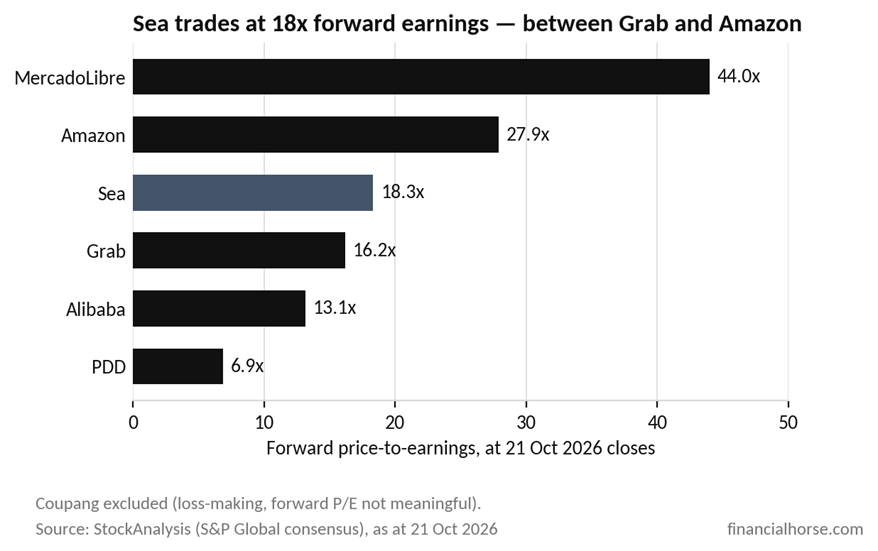
At US$78, Sea trades at about 18 times forward earnings, and 1.4 times sales.
MercadoLibre is on 44 times. Amazon 28. Grab 16, Alibaba 13, PDD 7.
So Sea is now priced like Alibaba and Grab – not like MercadoLibre – for a business growing revenue at 48%.
One honest caveat on the “US$9 billion of cash” you’ll see quoted – US$4.3 billion of customer deposits sit on the other side of the balance sheet funding Monee’s loans, so not all of it is available to be spent on GPUs.
Which is a fancy way of saying Sea is somewhat cheap at this price – if you assume the capex is modest, Shopee’s margins turn up, and the macro backdrop clears.
Which as you can imagine, is a very big if.
The Iran war decides everything if you ask me
That said.
I don’t think you can analyse Sea in isolation right now.
Much of this market depends on the Iran war, and Sea more than most.
The US 10-year yield sits at 5.1% – still above the 5% level I’ve been calling the danger zone for months.
Oil is at US$112, within a couple of dollars of its 4-year high..
And the Fed is now pricing in a hike in December, not a cut.
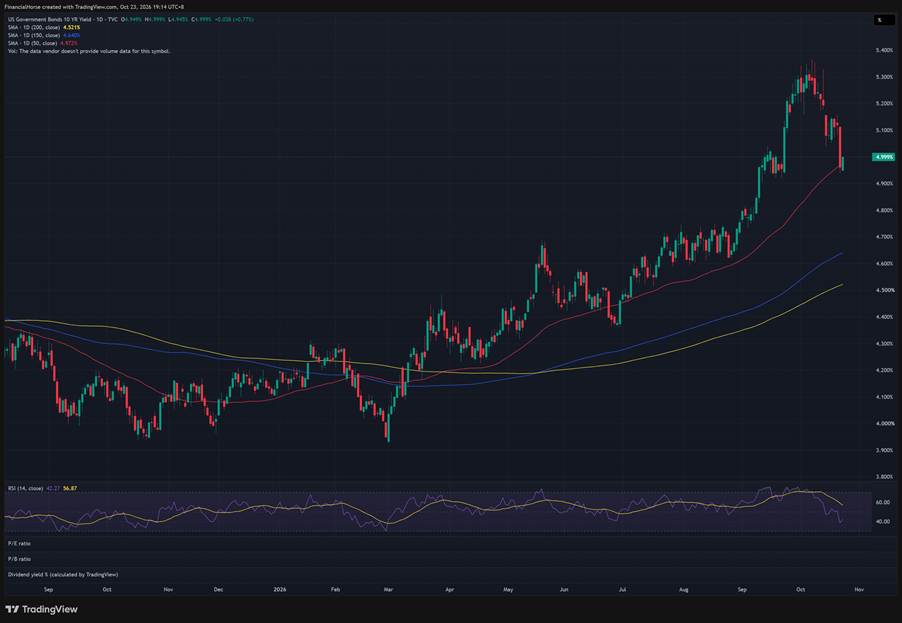
Why does that matter so much for Sea specifically?
Sea is a long-duration growth stock – you are paying today for earnings in 2028 and 2029, and a 5% risk-free rate leads to multiple compress – 25 times earnings to 18.
Meanwhile higher oil means a stronger dollar and weaker Southeast Asian currencies. That’s a double whammy because squeezed consumers spend less, and Sea earns less after accounting for FX.
There’s 2 ways this plays out (and this applies to the market generally).
Either the Iran war ends soon, yields come down, and there is relief for everyone – in which case Sea might see a huge relief rally.
Or it doesn’t end, and boy more pain will come for the market generally.
Risk-reward – buy, hold or sell Sea Ltd?
Keeping this simple – at US$78, I see 3 ways the next 2–3 years could play out:
Bull — the war ends, yields fall back below 5%, Shopee hits its US$1 billion profit ambition this year and Sea sizes the cloud spend at something reasonable. The market goes back to paying a growth multiple on earnings that finally grow. Total return maybe around +60–80% or more.
Base — analysts are roughly right on earnings and the cloud is a modest spend, but yields stay elevated and the multiple stays where it is. You get the earnings growth and nothing else. Total return maybe around +20–30% over 2–3 years.
Bear — the war drags on, the Southeast Asian consumer weakens, Monee’s bad loans rise, and the cloud turns out to be a US$2–3 billion a year commitment. Earnings stall, and 18 times becomes 12 times. Total return around −30–40%.
Is that attractive risk-reward?
Frankly – it really goes back to what happens with Iran, because that has a massive impact on which of the 3 scenarios we’ll see.
What I’m doing with my money – Buy or sell?
Sea is one of my larger Southeast Asian internet position.
My average price is around the US$100 mark, so I am down, but it’s probably not as bad as other investors whose average price is close to 200.
Am I buying more here?
I think the challenge with a chart like that – is that this is clearly a falling knife.
The stock broke below the 52 week low this week, and with a chart like that, good luck trying to call the bottom.
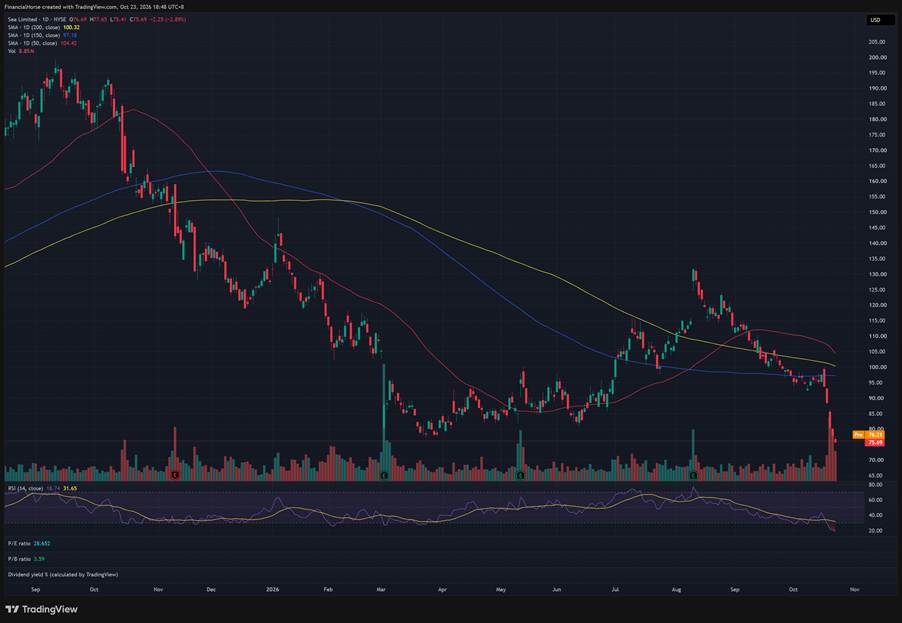
My own bias is to average into losers, and because of that my trading rules prohibit me from buying into a falling knife – which is exactly the case here.
Perhaps the better question is would I sell my stock?
I bought the stock originally on a turnaround play, on Monee and Shopee turning profitable.
With recent evidence, it suggests we are not nearing that point.
Shopee is still not generating big profits, and is getting squeezed by the Iran war, and now Sea is going to open up a new business line that requires massive capex.
The road to profitability for Sea just got pushed out – and by how long who knows.
Considering I’m down 20% ish on this position, it’s not too bad a loss, and I could sell into a bounce and get a good chunk of my capital back.
So would I sell?
Frankly, I’ve not made up my mind on this one.
If I do decide to sell, or add, I will share it on FH Premium as and when I make up my mind.
Love to hear what you think though!
This article was written on 23 Oct 2026. It will not be updated going forward.
My live views on Sea Ltd — including the price at which I would buy, and whether I’m still holding — are updated weekly on FH Premium, alongside my full watchlist and personal portfolio.
Join the FH mailing list and new articles land straight in your inbox:
Also on WhatsApp, Telegram and Facebook.