Back in May I wrote that Ascendas REIT had dropped to COVID prices, at S$2.49.
Well, it has fallen another 8% since then.
This week it traded at S$2.28 – the lowest price since the March 2020 crash.
And this is happening while DBS and OCBC sit near record highs, and the STI is up 22% this year.
That being said, the S-REIT sector is down about 13% in 2026. Ascendas REIT is down 19%.
So this is not just “REITs are down”, it looks like Ascendas REIT is doing especially badly even among REITs.
So… Will I sell this REIT, or buy more?
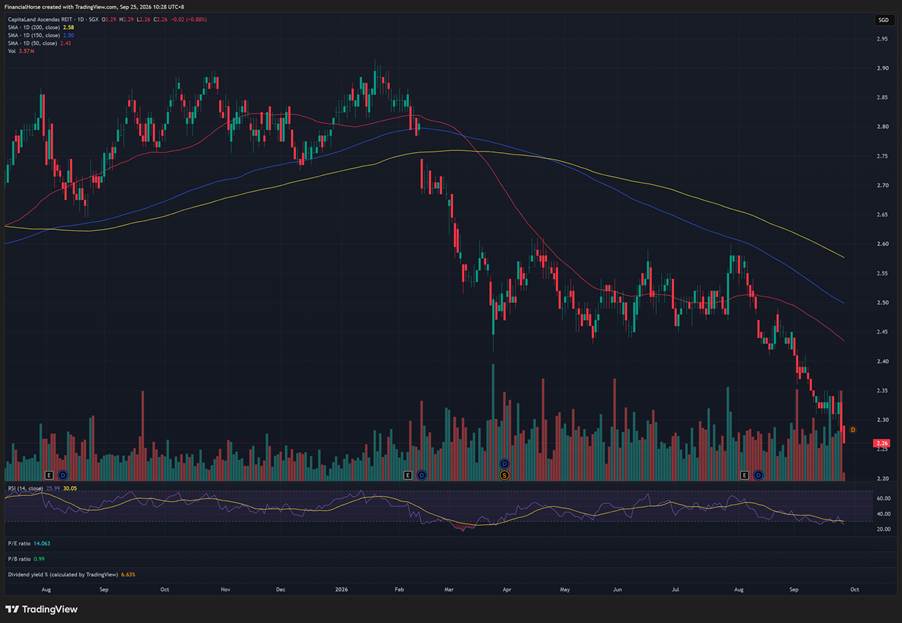
Price action of Ascendas REIT
Here’s the chart for reference.
Ascendas REIT has been on a downtrend down all year.
The REIT peaked at S$2.90 on 20 January, and every bounce since then has topped out lower.
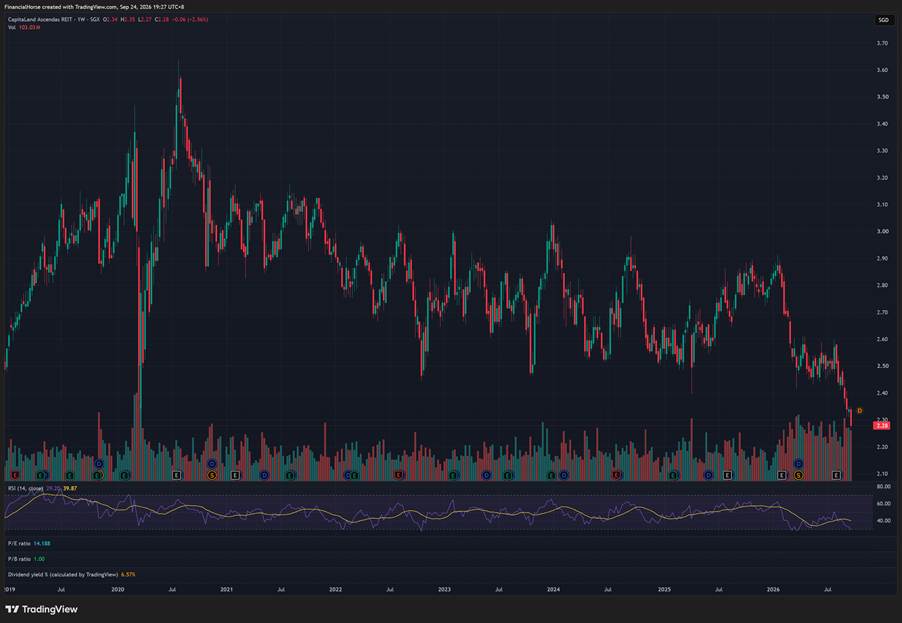
The floor that held in October 2022 (S$2.47) and again in October 2023 (S$2.48) gave way in August.
In plain English – in the last 2 interest rate shocks, Ascendas REIT bottomed in the high S$2.40s. This time it went straight through.
At current price – Ascendas REIT at $2.28 trades at prices last seen in 2020’s COVID crash.
What I said in May
In May, at S$2.49, I gave 3 reasons for the fall: the Iran war and oil, the overhang from the S$2.35 preferential offering, and the fact that about a quarter of the portfolio sits on land with less than 30 years of lease left.
I also said the REIT looked interesting at that price – but that it was a falling knife, and hard to call a bottom.
Well – the falling-knife call was absolutely spot on in hindsight.
How much of this fall is due to interest rates?
Here’s how the REIT sector has done in 2026.
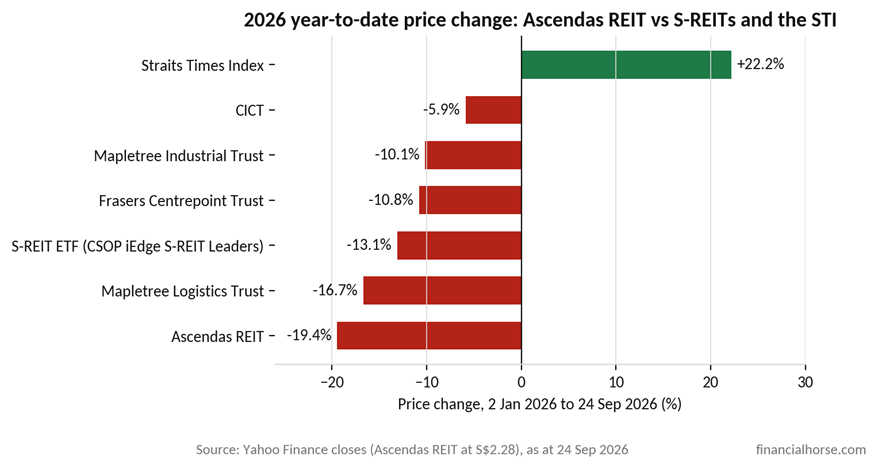
Every REIT on that chart is down, while the STI is up 22%.
The reason is simple – interest rates.
On 16 September the Fed raised rates by 25 basis points to 3.75–4.00%, its first hike since 2023, with one more pencilled in before year end.
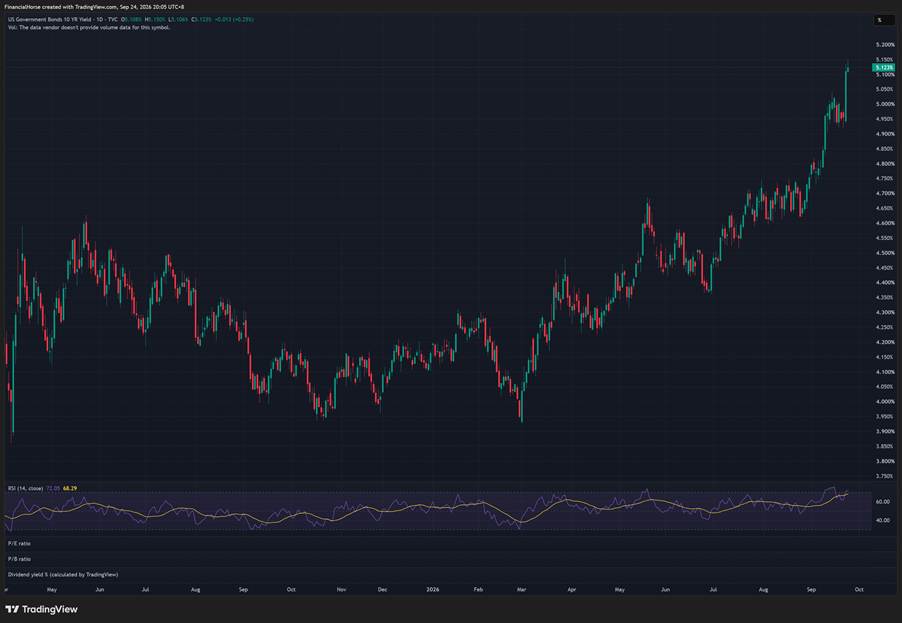
The US 10-year yield hit 5.11% on 23 September – the highest since 2007.
And the Singapore 10-year has gone from 1.74% at the start of the year to 2.49%.
In plain English – REITs are yield instruments, and priced against the risk free interest rate.
When the risk-free rate goes up 75 basis points, the price has to fall even if the distribution does not change.
Which is why REITs have been clobbered.
I wrote about this in more detail in the S-REITs piece earlier this month (the 3 interest rates that matter, and why SORA at 1.2% is actually a tailwind), so check that out if you are keen.
But if Ascendas REIT had simply tracked the S-REIT sector this year, it would be at around S$2.46 today.
It is at S$2.28.
So the sector explains about two-thirds of the fall.
The last third is Ascendas REIT’s own doing – and worth discussing.
What is wrong with Ascendas REIT specifically?
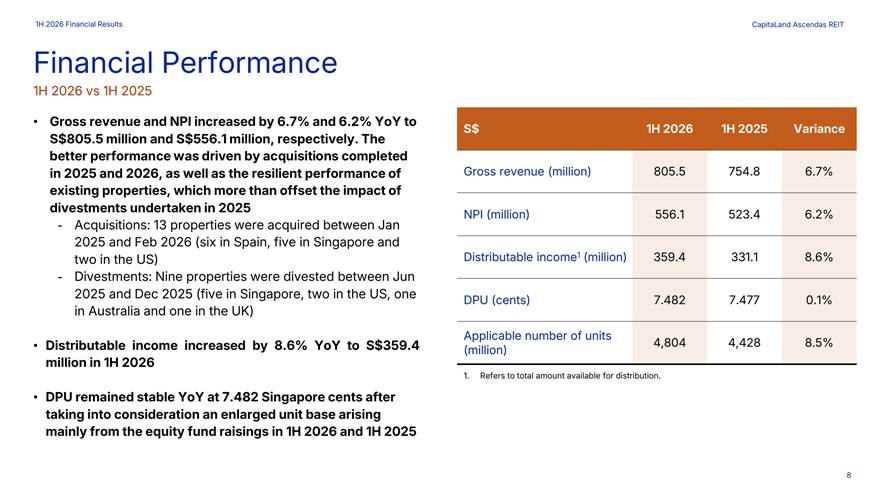
The 1H 2026 results, released in August, were not bad.
Gross revenue up 6.7%, net property income up 6.2%, distributable income up 8.6%.
Rental reversions of +8.5%, with full-year guidance raised to high single digit.
Gearing came down from 42.0% to 39.7%, and the cost of debt is 3.5% and falling.
Here is the REIT’s own summary of the half – pretty decent numbers.
And yet the unit is at 2020 prices.
So what exactly is the market concerned about?
My view, and of course I could be wrong on this, is that it comes down to 3 things.
One – the DPU has been flat / down for years.
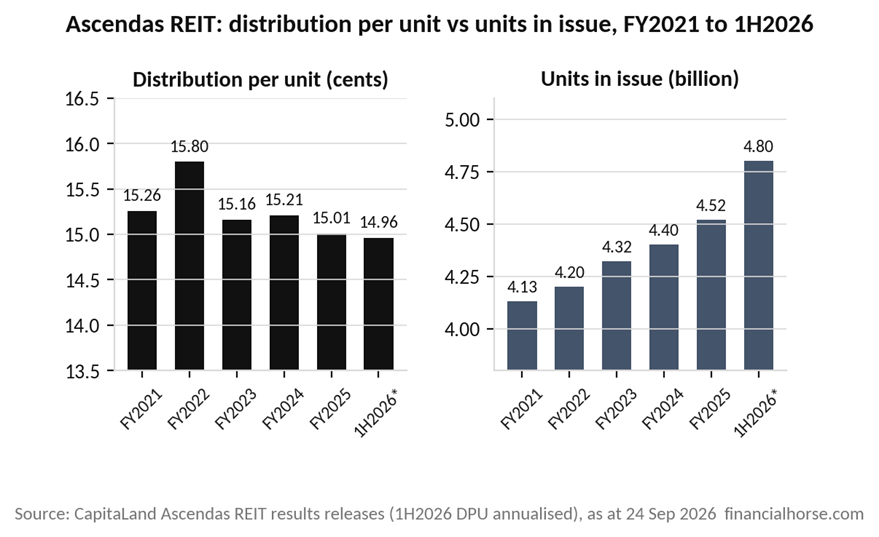
Here’s the DPU against the number of units.
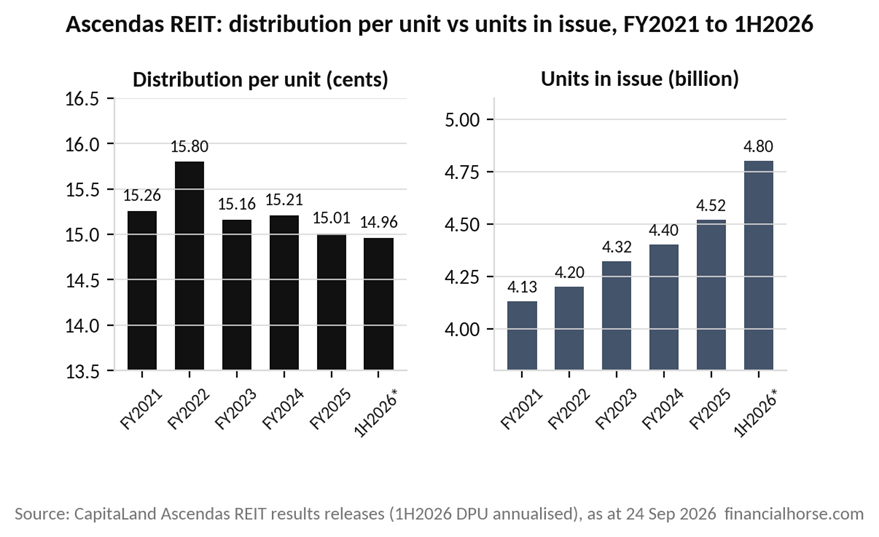
Ascendas REIT has paid 15.26, 15.80, 15.16, 15.21 and 15.01 cents a unit over the last 5 financial years.
Over the same period the number of units went from 4.1 billion to 4.8 billion – up 16% – and after the March placement there are now 5.0 billion units in issue.
In the latest half year, distributable income rose 8.6%. Distribution per unit rose 0.1%.
In plain English – REIT keeps buying new properties, and rental income keeps going up, but every dollar of new income arrives with a new unit attached to it. The whole gain went to the new units.
The manager is paid 0.5% a year of the property under management, so growing the assets without growing the DPU is perfectly rational – for the manager.
But for unitholders, all that growth has not translated into a higher DPU.
Five years of acquisitions, five years of good rental reversions, and despite all that the DPU is lower than it was in 2022.
I mean I myself am a unitholder, and looking at a chart like that is tough.
Two – everyone who funded the last 2 equity raises is underwater.
In June 2025 Ascendas REIT raised S$500 million at S$2.47.
In March this year it raised another S$903 million – at S$2.406 for the placement, and S$2.35 for the preferential offering.
Every one of those prices is above S$2.28.
So the investors who supported the last 2 raises are sitting on losses, and are not lining up to buy more.
I know not everyone believes this kind of analysis, but my experience is that there is a certain level of truth to it.
When many shareholders are sitting on losses, once it returns to a level they are no longer underwater, it creates a certain level of selling pressure as investors feel they are back in the green.
Three – Occupancy levels are not amazing.
Portfolio occupancy is 89.1%, against 91% at Mapletree Industrial Trust and 96% at Mapletree Logistics Trust and Frasers Logistics & Commercial Trust.
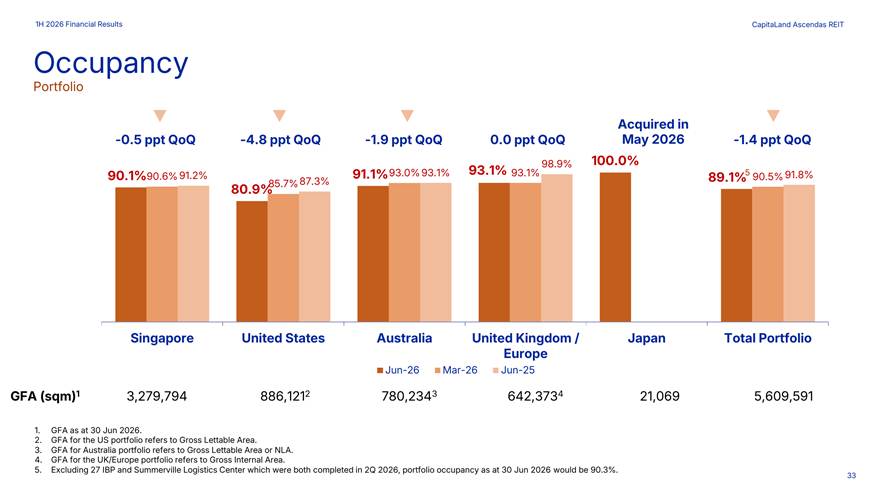
Some of it is temporary. 27 International Business Park was handed over 19% leased, with a target of 50–60% by year end. Geneo, the S$1.4 billion science park development, opened in May and is still leasing up.
Some of it is not obviously temporary. The US portfolio fell to 80.9% occupancy after a logistics tenant in Charleston left, and a business park building in Sydney went from 95% to 54% occupied on a lease expiry.
This is real vacancy in specific buildings, not macro softness.
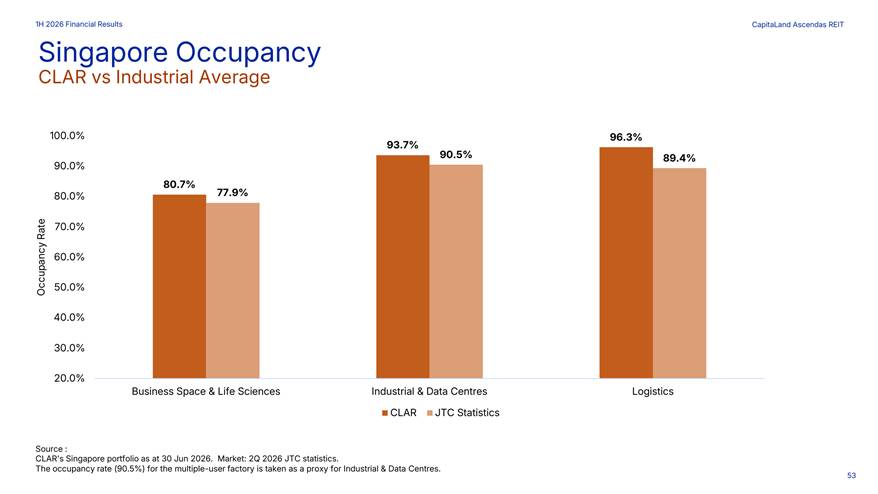
In Singapore itself, Ascendas REIT is actually ahead of the market in every segment – but business space is soft across the whole island.
To be fair – there is likely zero insolvency risk here.
Gearing is 39.7% and falling.
Interest cover is about 3.5 times.
70% of the debt is fixed.
Kim Chuan Telecommunications Complex was sold in July for S$200 million, 32% above its book value – so the book values are conservative, and the manager will sell when the price is right.
So there is no insolvency risk here, and for what it’s worth it remains a solid blue chip REIT.
Never miss a post! Follow Financial Horse on WhatsApp or Telegram — one tap, and every new article reaches you the moment it’s published.
What’s priced in at S$2.28?
At S$2.28, Ascendas REIT pays a trailing yield of 6.6%.
It trades at roughly book value (NAV of S$2.27 a unit), and at about 15 times forward distributions – the cheapest since March 2020, and cheaper than the October 2022 and October 2023 lows.
Here’s how the yield compares with the alternatives:
| Instrument | Yield | As at |
| Ascendas REIT | 6.6% | 24 Sep 2026 |
| Mapletree Industrial Trust | 6.5% | 10 Sep 2026 |
| Mapletree Logistics Trust | 6.4% | 4 Sep 2026 |
| Frasers Logistics & Commercial Trust | 6.4% | 11 Sep 2026 |
| CICT | 5.2% | 18 Sep 2026 |
| 10-year SGS | 2.49% | 24 Sep 2026 |
| 6-month T-bill | 1.70% | 10 Sep 2026 |
And here’s how the operating numbers compare:
| REIT | Latest DPU (y/y) | Occupancy | Gearing |
| Ascendas REIT | +0.1% | 89.1% | 39.7% |
| Mapletree Industrial Trust | −2.5% | 91.2% | 34.0% |
| Mapletree Logistics Trust | +0.2% | 96.4% | 40.5% |
| Frasers Logistics & Commercial Trust | flat | 96.1% | 35.4% |
You can see the problem.
On yield, Ascendas REIT is mid-pack – the same 6.4–6.6% as the other big industrial REITs.
On gearing, it is no worse than the peers.
On occupancy, it is the worst of the group.
I suppose to put it bluntly, the market thinks of Ascendas REIT as the UOB of the local banks.
The discount is the market way of saying that structurally the DPU may not grow going forward – which is exactly what it has done for 5 years.
What I’m doing with my units
Personally I hold Ascendas REIT, but my average price is about 2.5, and after including dividends I am probably in the green, but not by much.
So now at S$2.28 I’ve got a decision to make.
Do I cut the position, or do I add more?
You know what, strange as it seems, I am inclined to do absolutely nothing for now.
While Ascendas REIT is cheap relative to its own history, there are 2 reasons that hold me back from adding.
First – it’s not clear from a macro perspective whether interest rates have peaked.
This all goes back to how the US-Iran war will play out, and boy good luck predicting that one.
Maybe Trump caves in tomorrow, maybe it’s June 2027 and the Strait is still closed. Who knows.
Secondly – it’s also clear from the market pricing that the market does not expect operational results to outperform.
So it’s kind of like the UOB situation here where nobody doubts that the REIT (or bank) is cheap, the question is whether it is cheap for a reason.
If you think Ascendas REIT can outperform expectations going forward, then yeah I agree current prices are cheap.
If Ascendas REIT’s DPU is going to continue to stay flat / drop though, then it’s very possible Ascendas REIT is cheap for a reason.
So for now at least, I’m not doing anything with my position at all, just letting it run and see what happens next.
The 6.6% yield is decent and as long as price stays flat for the next year I would already be up 6.6%. And any capital gains on top of that is pure upside.
But at the same time, I already have a position, and given the factors above I’m not sure if I want to add to it.
That being said I reserve the right to change my mind any time, and my latest views would be shared on FH Premium.
For those of you holding Ascendas REIT – are you adding at S$2.28, holding for the yield like me, or have you cut it? And what do you think the market sees that the brokers with S$3 targets do not?
Love to hear what you think!
This article was written on 24 Sep 2026. It will not be updated going forward.
My live views on Ascendas REIT — including the price at which I would buy — are updated weekly on FH Premium, alongside my full watchlist and personal portfolio.
Join the FH mailing list and new articles land straight in your inbox:
Also on WhatsApp, Telegram and Facebook.
Thank you for the timely very detail analysis of ascendas.
I have a small position in it and thinking of adding to collect dividends.
Have been patiently holding on to fire till may be it reaches closer to $2-2.05.
Always enjoy your sharing and like to thank you for your time and effort.
With best wishes
Yau🙏🤗